
Defense Tech Goes Mainstream: What the Autonomy Investment Wave Means for Founders
October 29, 2026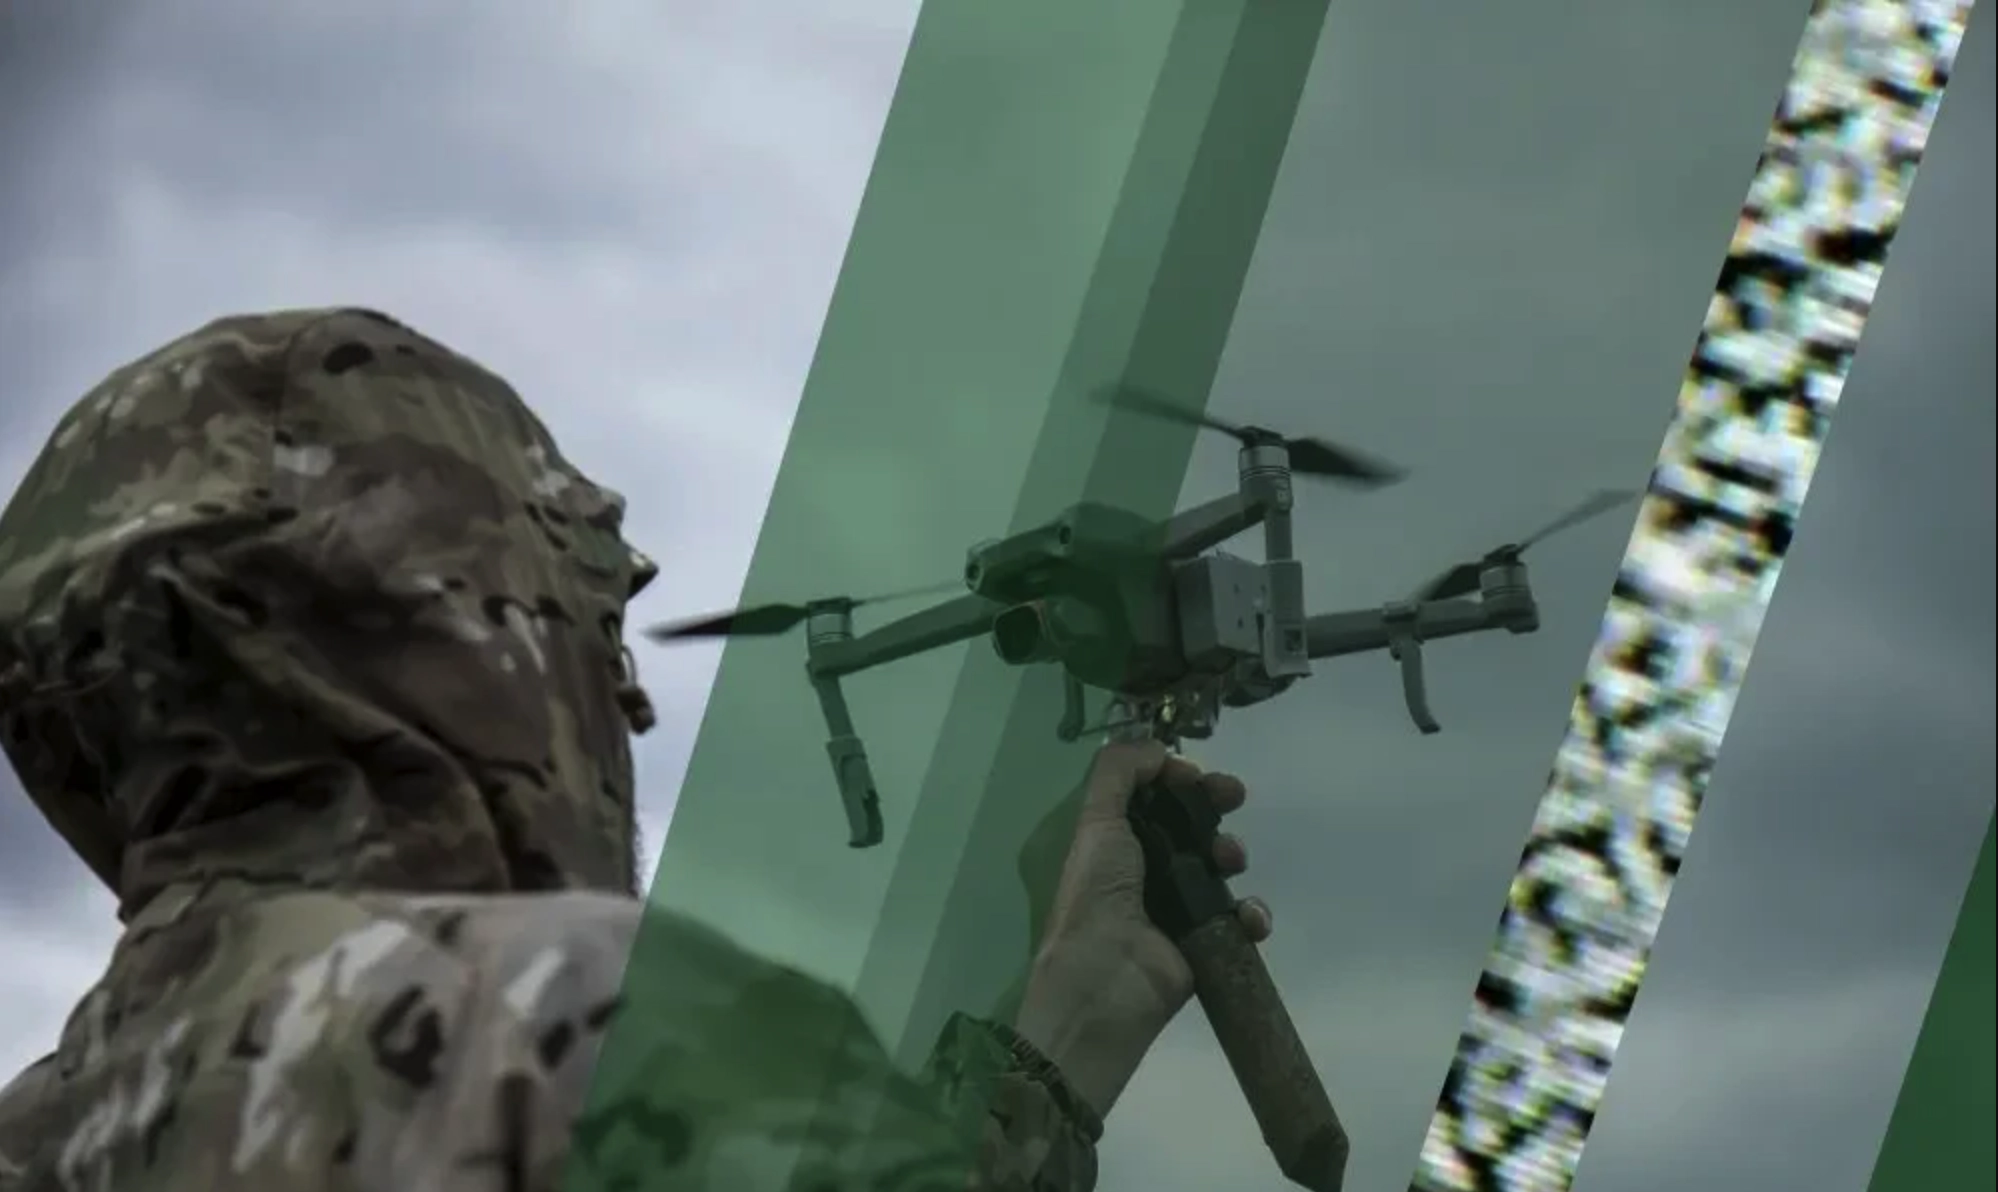


Defense and autonomy have moved from niche to mainstream capital targets in 2026. Through Q3, J.P. Morgan’s quarterly venture analysis tracked record deal sizes in AI infrastructure companies serving defense clients alongside commercial markets, a pattern that was barely visible two years ago.
The shift is structural. Geopolitical pressures, the commercial viability of AI-driven autonomy systems, and the success of dual-use companies in attracting both government contracts and enterprise customers have made this a permanent fixture in mainstream venture portfolios.
From Specialty Category to Structural Allocation
Two years ago, institutional venture capital treated defense technology as a specialty category best left to firms with government contracting expertise. That consensus has broken down.
The clearest indicator comes from October 2026 deal flow. Value Add VC tracked the largest October checks going to a chip company, a developer tools platform, and an AI infrastructure company with visible defense clients. None of these were positioned as defense-first businesses. They were infrastructure companies that happened to serve defense customers profitably alongside commercial ones.
Dual-use positioning has shifted from a liability to a funding advantage. Investors see defense revenue as non-cyclical and high-value, while commercial customers validate market adoption at scale. Defense-adjacent autonomy led the fastest-growing European VC verticals by deal count through the third quarter.
What Investors Actually Evaluate
Venture capital interest in autonomy and defense technology follows a specific pattern in 2026. Investors are not backing traditional defense contractors or hardware-heavy programs with decade-long procurement cycles. They are backing software-first companies that can serve commercial markets today and defense customers at scale.
The criteria that matter in technical due diligence for this category:
- Software-first architecture: Investors prioritize companies where the defensible value sits in the software layer. This reduces capital intensity and speeds up go-to-market timelines.
- Dual-use customer base: A commercial customer base alongside defense interest reduces procurement concentration risk and demonstrates market validation outside government channels.
- Mission-critical engineering experience: Founders with backgrounds in systems integration, regulated environments, or safety-critical software carry a meaningful advantage in investor conversations.
- Clean IP ownership: Intellectual property clarity matters more in this category than in consumer software. Government contracts scrutinize it carefully.
What This Means for Early-Stage Founders
The mainstream capital moment does not make the category easy to enter. Competition at pre-seed and seed has intensified as generalist investors add autonomy to their investment theses.
Founders who secure funding in this environment share a common characteristic: they are specific about the problem, not general about the category. A company solving a defined logistics routing problem for commercial fleets that also works for military logistics chains is more fundable than a company positioned broadly as an autonomy platform.
The most useful signal from Q3 2026 is that the window for early-stage capital is open, but investor patience for abstract positioning has shortened. The bar is a working prototype, a named customer, and a clear explanation of why your specific team can solve this specific problem.
Contact us to discuss how IGF can support your deep tech startup.
View more articles
Browse our collection of articles below and embark on a journey of discovery.